TAX & BUSINESS
All Forms
Find wage statements, taxpayer information forms and business documents.
Browse forms
Explore the regular employee Medicare deduction and the extra withholding triggered when wages from one employer pass $200,000.
Use the calculator free. Preparing a pay stub is a separate paid service.
Pay stub designs · Simple starts at $3.99 ↗
Calculate this employee tax on its own.
Annual employee tax reference
Employee Medicare withholding only. Final Additional Medicare liability and insurance premiums are separate.
| Tax component | Amount |
|---|---|
| Regular employee Medicare · 1.45% | $1,087.50 |
| Additional Medicare withholding · 0.9% | $0.00 |
| Total employee tax | $1,087.50 |
Each average is rounded separately. Adding the rounded components may differ from the rounded total by one cent.
Example: $75,000 annual covered wages · 2026
Estimating pay costs nothing. Document preparation is a separate purchase: enter figures from your records, choose a layout and check the preview.
Simple costs $3.99 per stub. Compare the price of your selected design and any extras before you pay.
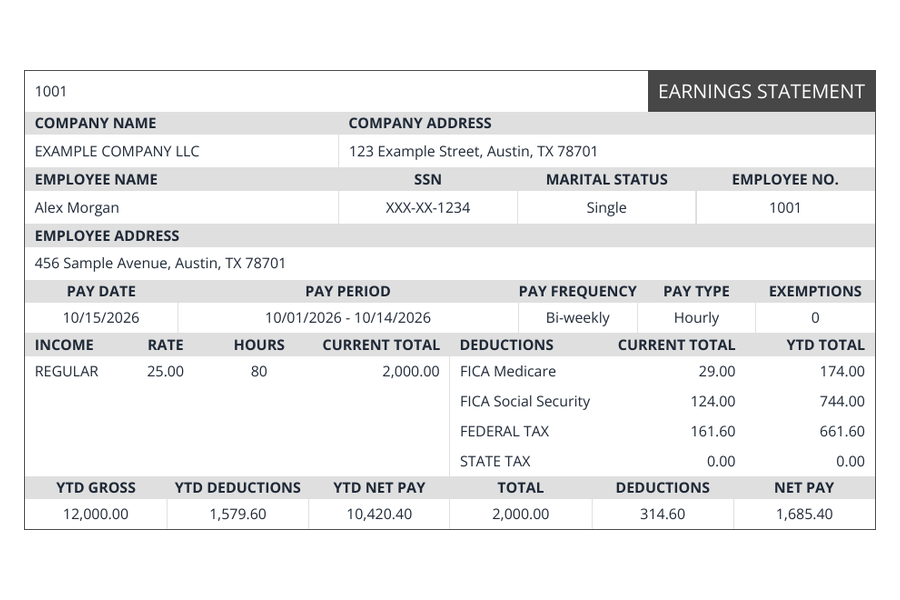
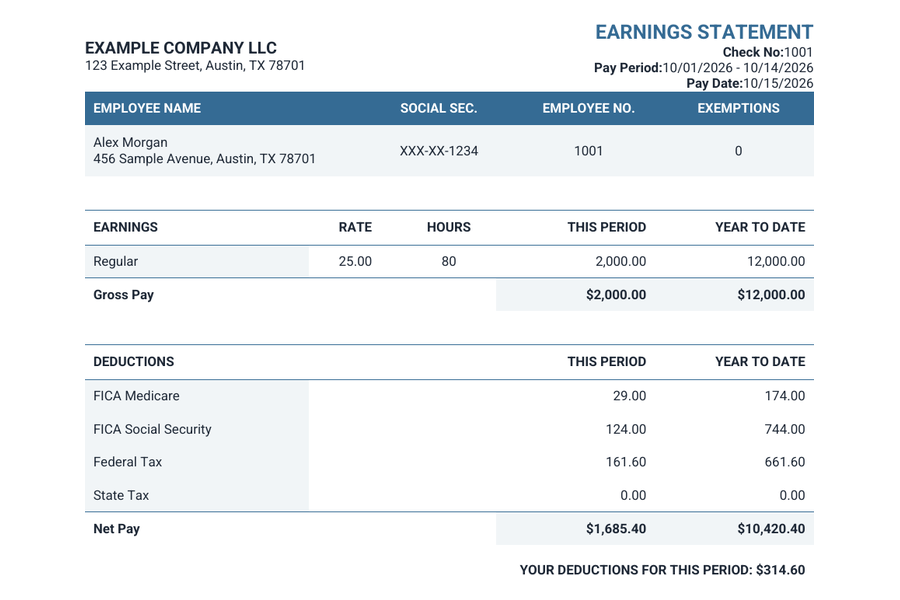
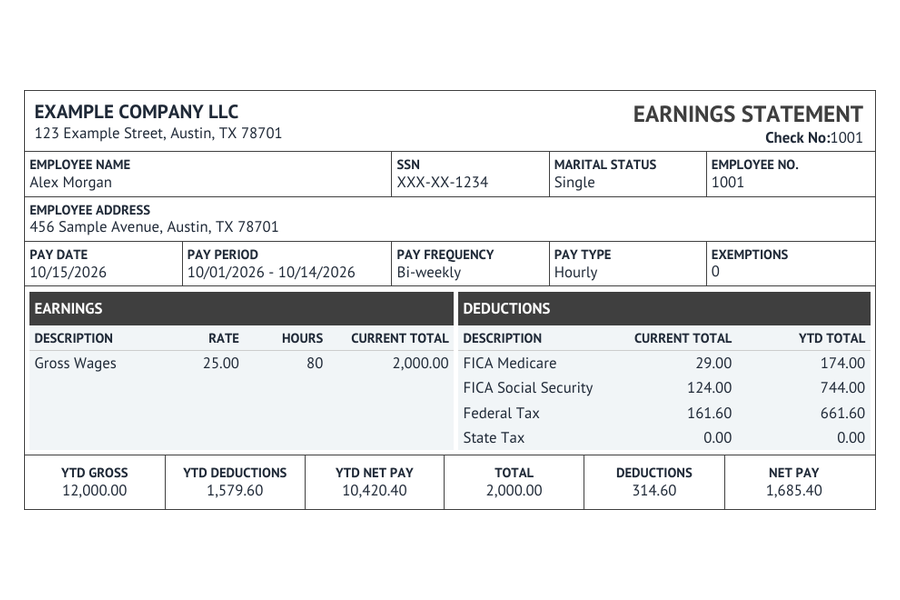
Illustrations use fictional details. Each design has its own price; calculator inputs stay separate from document orders.
Find wage statements, taxpayer information forms and business documents.
Browse formsBring the position, compensation and employment terms into one letter.
Create an offer letterDescribe your services, itemize charges and make payment details easy to find.
Explore invoicesOrdinary Medicare-covered employee wages have a 1.45% payroll deduction with no annual wage cap. Additional Medicare withholding is a separate 0.9% calculation.
An employer begins Additional Medicare withholding on wages it pays above $200,000 during the calendar year. That payroll trigger is the same for all filing statuses. The ordinary 1.45% deduction continues on covered wages above the trigger as well.
Enter current Medicare-covered wages and prior covered wages from the same employer and year, before this check. The tool applies 1.45% to the check and 0.9% only to the portion that crosses or remains above the employer trigger. Zero prior wages assumes no earlier covered wages with that employer.
Annual mode calculates the two employee components once for annual covered wages. Average figures divide that reference; they do not show which actual check crosses $200,000. Rounding payroll check by check can produce a different annual total.
Additional Medicare liability on a return uses thresholds of $250,000 for married filing jointly, $125,000 for married filing separately and $200,000 for other taxpayers. Household wages and certain other income can matter. Those thresholds do not replace the employer’s $200,000 withholding rule, and this tool does not reconcile final liability.
With $199,000 in prior Medicare-covered wages and a $3,000 check, the ordinary employee deduction is $43.50. Of this check, $2,000 is above the employer trigger, adding $18.00. The combined employee Medicare withholding is $61.50. This example is a payroll calculation, not a final-return liability determination.
No. The employer withholding trigger remains $200,000. Filing-status thresholds apply to the separate final-return liability test.
No. Medicare has no annual covered-wage cap. Social Security has a separate annual limit.
No. It estimates the employee payroll deduction only, excluding the employer share, Medicare insurance premiums, self-employment tax and special employment arrangements.
Select the payroll year you want to model and supply the correct taxable or covered wage basis. This calculator does not classify benefits or decide whether wages are taxable.
Rules were reviewed on October 26, 2026 for the two supported years. Later changes require another review. Use the result as a planning comparison alongside payroll records, rather than as a tax-return calculation.
Enter earnings and deductions from your records, select a document design and review the preview before payment.