ORIGINAL ISSUE DISCOUNTForm 1099-OID.
Form 1099-OID.
OID reporting, in one place.
Arrange original issue discount and related reporting figures on Form 1099-OID from the records you have prepared.
$9.99USD per form
Complete PDF · Preview free
Pay when ready to download
Available tax years: 2025 and 2026 · Preview before checkout
YOUR 1099-OID PREVIEWCopy B · Recipient
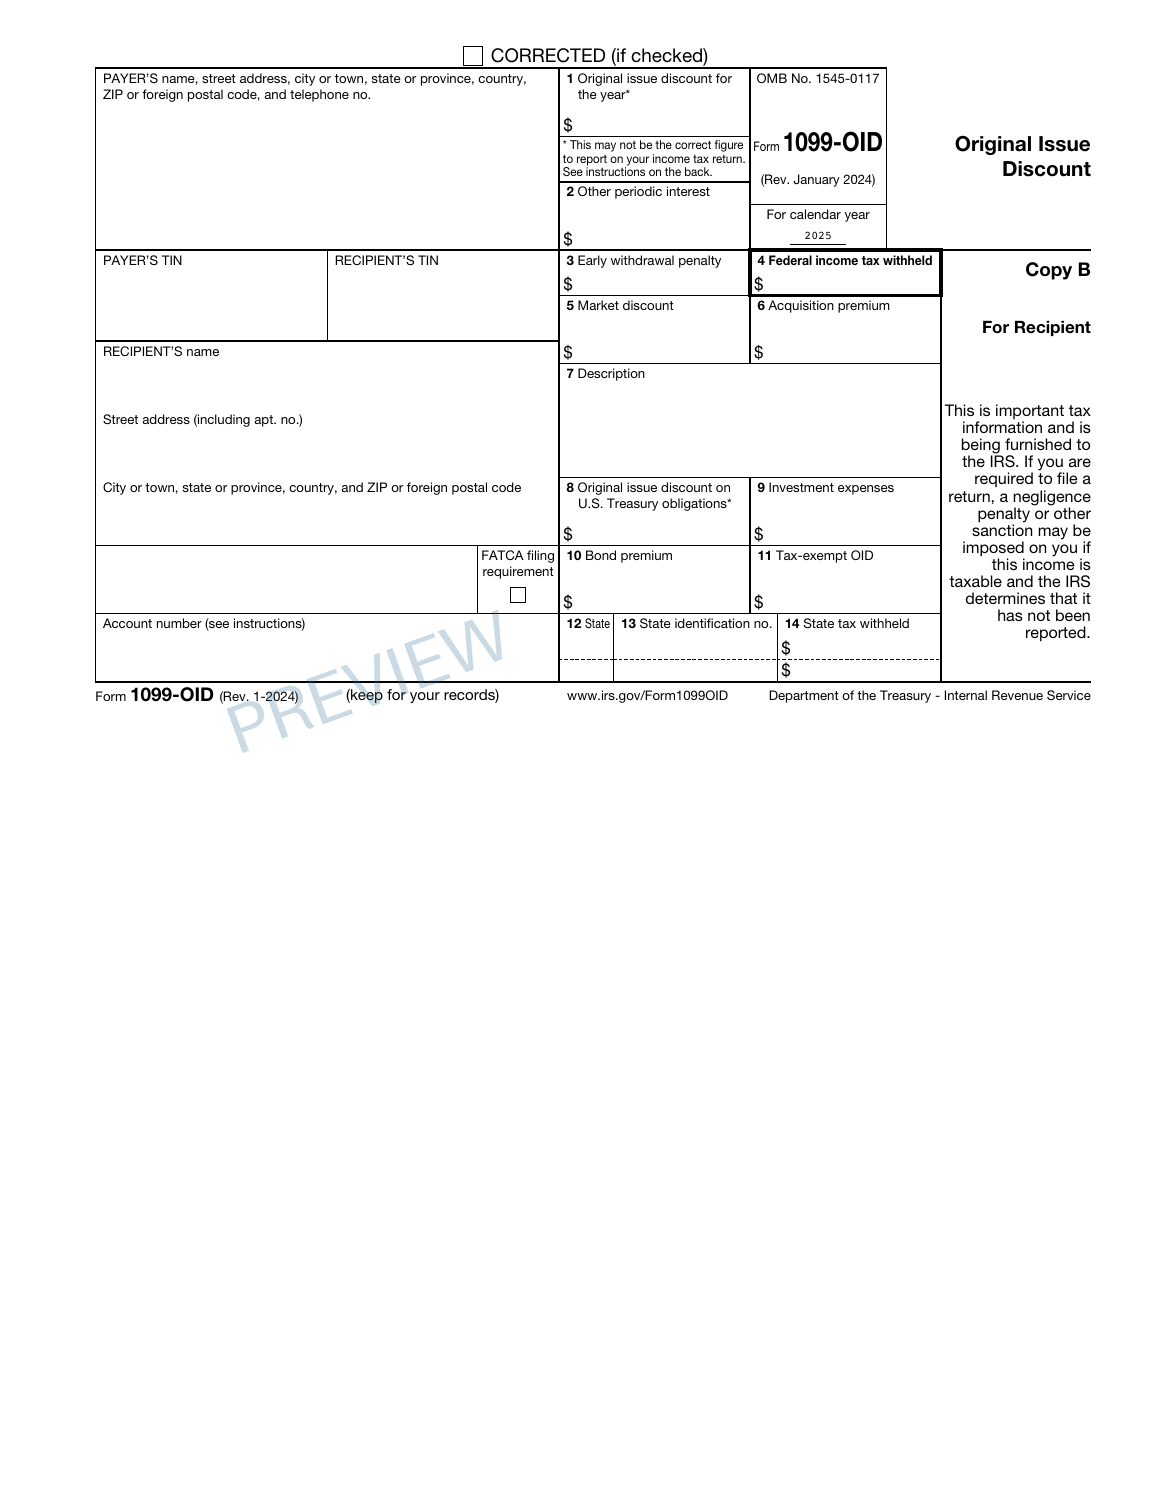
Your payment records, clearly presented.
✓ Preview every page✓ Correct IRS revision for each year✓ Private order access
PREPARE WITH YOUR RECORDS
Before you create your 1099-OID.
Keep OID amounts, stated interest and associated adjustments distinct. The form is a record of those figures, not a substitute for determining them.
Prepared OID and interest amounts
Withholding and applicable adjustment records
THE DOCUMENT AND ITS LIMITS
Your PDF. Its purpose.
The document copies organize the original issue discount, interest, adjustment and recorded withholding information entered in the workspace. Keep the source reporting calculations available while checking the populated boxes.
The service does not calculate every OID accrual or adjustment, determine the recipient’s tax or file an information return.
Check the official IRS 1099-OID information and instructions for filing requirements and supporting worksheets.
A FEW POINTS TO CHECK1099-OID questions,
1099-OID questions,
before you begin.
Will the form calculate the original issue discount for an investment?
No. Establish the reportable figures from the relevant records and calculations first. The builder places those amounts in the supported reporting fields so you can inspect the completed statement.
How can I check the 1099-OID before purchasing?
Complete the required entries and inspect the available preview pages. Reconcile the names, dates and figures with your source records before continuing to checkout.
What does the 1099-OID PDF cost?
$9.99 USD covers one form prepared with this builder. Review the supported edition, your entries and the complete order total before paying.
Can I return to this 1099-OID later?
Use Save for later to create a private editing link valid for 30 days. Completed-order access lasts 90 days. Keep those links secure and download your finished PDF for your own records.
FROM YOUR RECORDS TO A REVIEWED PDF
Open the builder Prepare your 1099-OID.
Start with your records. Check the preview. Complete your document when it is ready.